The EV Battery Race: Indonesia’s Downstream Bet
How Indonesia’s nickel reserves and downstream processing mandate are reshaping the global electric vehicle supply chain — and where the opportunities lie.
Indonesia is making one of the most consequential bets in the global electric vehicle supply chain: turn its extraordinary nickel endowment into an integrated battery and EV industry.
The strategy is straightforward in principle.
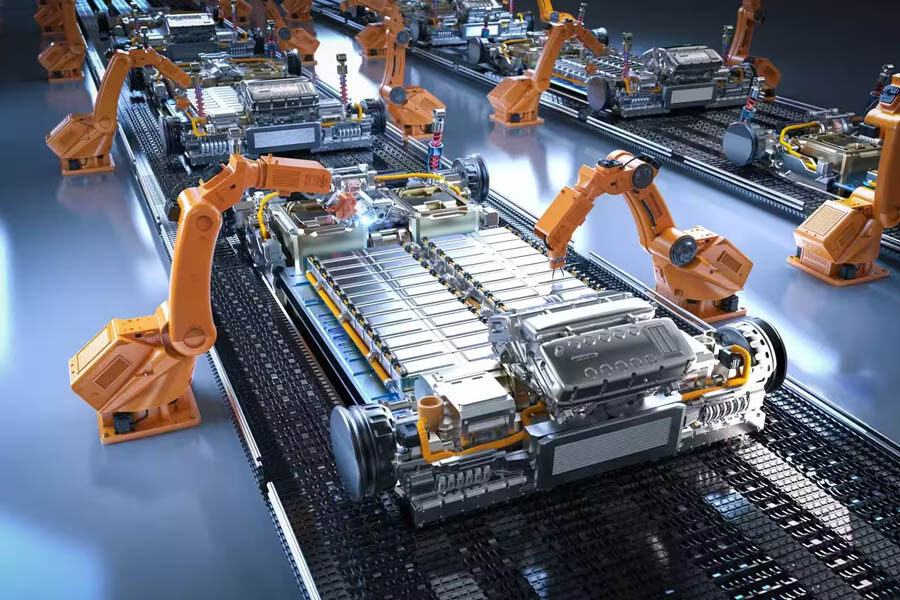
Rather than exporting raw nickel ore, Indonesia wants more of the value chain to take place domestically—from mining and refining to battery materials, battery cells, and ultimately electric vehicles.
The policy has already transformed Indonesia’s mining and industrial landscape. Since the country progressively restricted nickel ore exports, with a full ban in effect from January 2020, investment has flowed into domestic processing capacity. The objective has been to capture more value, create jobs, and build industrial capability inside Indonesia.
But the next phase is more complicated.
Indonesia is no longer simply asking:
“How can we process more nickel?”
The strategic question is:
“How can Indonesia build a globally competitive battery ecosystem—and capture sustainable value as battery technology, demand, and supply chains evolve?”
From Nickel Producer to Battery Powerhouse
Indonesia has one of the world’s largest nickel endowments. The Indonesian Geological Agency, citing USGS data, says more than 40% of global nickel reserves are located in Indonesia.
This resource advantage has made nickel the cornerstone of Indonesia’s downstream industrial strategy.
But ore is only the beginning of the battery value chain.
The emerging ecosystem increasingly includes:
Nickel ore → processing and refining → MHP → nickel sulfate → precursor → cathode active material → battery cells → electric vehicles
Indonesia’s ambition is to move progressively along this chain.
In January 2026, the government highlighted a new integrated battery ecosystem initiative involving state miner ANTAM, Indonesia Battery Corporation, and a Chinese consortium led by Zhejiang Huayou Cobalt. The proposed US$6 billion project is designed to cover activities ranging from nickel mining and processing to cathode production and battery cells.
The direction is clear:
Indonesia wants to capture more of the battery value chain at home.
The Downstream Mandate
Indonesia’s downstream strategy is not simply an industrial preference.
It is a deliberate policy instrument.
The nickel ore export restrictions were designed to encourage domestic processing and retain more economic value within Indonesia.
The result has been a dramatic expansion of domestic nickel processing.
But policymakers are increasingly looking beyond the traditional stainless-steel route.
Indonesia’s earlier nickel boom was heavily associated with products such as nickel pig iron and ferronickel. The next policy objective is to move further into higher-value battery materials and EV manufacturing.
This distinction matters.
A country can become a major nickel processor without becoming a major battery manufacturer.
Indonesia is attempting to make the second transition.
The Battery Opportunity Is Moving Midstream
One of the most interesting areas of opportunity is no longer simply mining.
It is midstream battery materials.
High Pressure Acid Leach (HPAL) technology allows lower-grade nickel resources to be processed into Mixed Hydroxide Precipitate (MHP), an important intermediate for battery-material production.
Indonesia is now expanding capabilities beyond MHP.
In July 2026, Indonesia’s Ministry of Investment and Downstream Industry highlighted the installation of the main autoclave equipment for the Sambalagi HPAL project in Central Sulawesi. The government described the project as part of a broader strategy spanning MHP, nickel sulfate, precursor, cathode active material, and EV batteries.
At the same time, international investors are looking further downstream. In June 2026, the Indonesian government discussed plans with Australia’s Pure Battery Technologies for a precursor cathode active material facility using MHP supplied from domestic HPAL operations.
This suggests an important shift:
The opportunity is expanding from extracting nickel to engineering an integrated materials ecosystem.
Indonesia’s Global Supply-Chain Advantage
Indonesia’s proposition is particularly powerful because of the combination of:
-
large nickel resources;
-
expanding refining capacity;
-
growing HPAL infrastructure;
-
industrial estates;
-
relatively large domestic market potential;
-
government support for downstream investment; and
-
an increasingly integrated battery ecosystem.
The International Energy Agency’s 2026 Global EV Outlook notes that Indonesia now has an anode active-material manufacturing pipeline larger than Japan’s or Korea’s, while its cathode active-material and cathode-precursor industries are also expanding rapidly.
This is significant.
It means Indonesia is beginning to move beyond the traditional role of a raw-material supplier and into parts of the global battery materials architecture.
But Nickel Is Not the Whole Battery Story
The biggest strategic risk is technological.
Indonesia’s downstream strategy has been built heavily around nickel-containing battery chemistries, particularly NMC.
But the battery market is changing.
LFP—lithium iron phosphate—has gained substantial market share because it avoids nickel and cobalt, while offering cost and supply-chain advantages.
The IEA reports that almost 80% of EV batteries deployed outside China in 2025 still used nickel-containing chemistries, but LFP continues to expand.
For Indonesia, this creates a critical strategic challenge.
The country may successfully build enormous nickel-processing capacity while global battery demand becomes less dependent on nickel.
This is why Indonesia’s downstream strategy cannot stop at nickel.
The long-term opportunity lies in developing flexible industrial capabilities that can remain competitive as battery chemistry evolves.
The Oversupply Question
There is another challenge: supply.
Indonesia’s rapid expansion helped make it the world’s dominant nickel producer, but the speed of capacity growth has contributed to periods of global oversupply and lower prices. Reuters reported in late 2025 that Indonesian nickel production had surged from approximately 780,000 tonnes in 2020 to 2.3 million tonnes in 2024, while concerns about prolonged oversupply remained.
The government’s response is becoming more active.
In June 2026, Indonesia’s Ministry of Energy and Mineral Resources said the 2026 nickel production plan was still under evaluation, emphasizing the need to assess supply and demand rather than automatically relaxing production limits.
This signals a broader transition.
The next phase of Indonesia’s nickel strategy may be less about maximizing volume and more about managing:
capacity + pricing + value addition + sustainability + market demand.
For investors, that distinction is critical.
The Sustainability Test
Indonesia’s battery opportunity increasingly faces another question:
Can Indonesian nickel become globally competitive on carbon intensity and sustainability?
Much of Indonesia’s nickel processing has historically depended heavily on coal-based power.
That creates challenges as international buyers, automakers, and investors increasingly scrutinize emissions, traceability, environmental performance, and social standards.
Recent market analysis has highlighted that verified lower-emission materials could become increasingly important as global carbon and traceability requirements tighten.
Indonesia is beginning to respond.
For example, the Sambalagi HPAL project has been designed with waste-heat recovery and solar power components as part of a lower-carbon operating model, according to the Indonesian Ministry of Investment and Downstream Industry.
This creates a new investment category:
Green downstreaming.
The opportunity is no longer only to build more processing capacity.
It is to build more competitive, lower-carbon processing capacity.
Where the Opportunities Lie
For international investors and strategic partners, the opportunity set is broader than nickel mining.
1. Battery Materials
MHP, nickel sulfate, precursors, cathode active materials, and other specialty materials represent opportunities to move further into the value chain.
2. Battery Manufacturing
Cell manufacturing and battery-pack assembly can capture additional value while strengthening Indonesia’s domestic EV ecosystem.
3. Industrial Technology
HPAL, process optimization, automation, materials engineering, waste management, and industrial digitalization can support the expansion of the ecosystem.
4. Low-Carbon Energy
Reliable, competitive, lower-carbon power will become increasingly important for Indonesian battery materials seeking access to sustainability-conscious global markets.
5. Recycling and Circular Economy
As Indonesia’s battery fleet grows, battery recycling and materials recovery will become increasingly important components of a mature domestic ecosystem.
6. EV Manufacturing
Battery localization creates a foundation for deeper integration with electric-vehicle manufacturing and related component industries.
7. Supply-Chain and Industrial Services
Logistics, ports, industrial infrastructure, testing, certification, engineering, maintenance, and specialized professional services will all be required as the ecosystem expands.
The Investment Question Is Changing
For the first generation of investors, the question was largely:
Where is the nickel?
For the next generation, the question is:
Where is the value being created?
That distinction is fundamental.
The strongest opportunities may not necessarily be in the largest mining projects.
They may sit at strategic bottlenecks in the value chain—where technology, infrastructure, financing, energy, regulation, and market access intersect.
Investors should therefore evaluate Indonesia not as a single nickel market, but as a developing industrial ecosystem.
Government Is Part of the Investment Equation
Indonesia’s EV battery strategy is deeply connected to government policy.
The downstream mandate, mining regulations, investment incentives, industrial-estate development, energy policy, environmental standards, and EV-related policies all influence investment outcomes.
This makes government engagement an important component of market strategy.
For international organizations, understanding the commercial opportunity is only one part of the equation.
They also need to understand:
-
which institutions shape the sector;
-
how policy priorities are evolving;
-
how regulations affect project economics;
-
where government support is concentrated;
-
how national and regional interests intersect; and
-
how the policy environment may evolve as the industry matures.
In Indonesia, market intelligence and institutional intelligence increasingly need to work together.
The Strategic Bet
Indonesia has made a clear strategic bet:
Use natural-resource advantage to build industrial capability.
The EV battery sector is one of the most ambitious expressions of that strategy.
The country has already demonstrated that policy can rapidly transform a commodity supply chain. The next challenge is proving that downstream investment can create durable competitive advantage rather than simply additional capacity.
That will depend on several factors:
Technology.
Energy.
Market demand.
Capital.
Regulatory stability.
Sustainability.
And the ability to build trusted international partnerships.
AMANTRA Perspective
At AMANTRA, we see Indonesia’s EV battery opportunity as more than a mining story.
It is a story about industrial transformation.
The country’s nickel advantage provides the foundation. Downstream policy provides the direction. International capital and technology can accelerate the development of the ecosystem.
But successful participation requires understanding the entire environment—from resources and industrial infrastructure to government policy, regulatory direction, technology trends, and international market requirements.
Indonesia is building a battery ecosystem.
The strategic opportunity for international organizations is to determine where they can contribute, where value will accumulate, and how to build a position that remains relevant as the industry evolves.
The EV battery race is not simply about who controls the raw material.
It is about who controls the capabilities, technologies, infrastructure, and relationships that turn raw materials into global value.
And Indonesia is betting that its next chapter will be written further downstream.